Loan Partner II
Caleb Andes
Keeps your file moving from application to processing.
Your Way Home
Loan OfficerMortgage Loan Officer, Cary, NCNMLS # 2643008
A few quick questions to give us a clear picture of your options - no credit pulls.
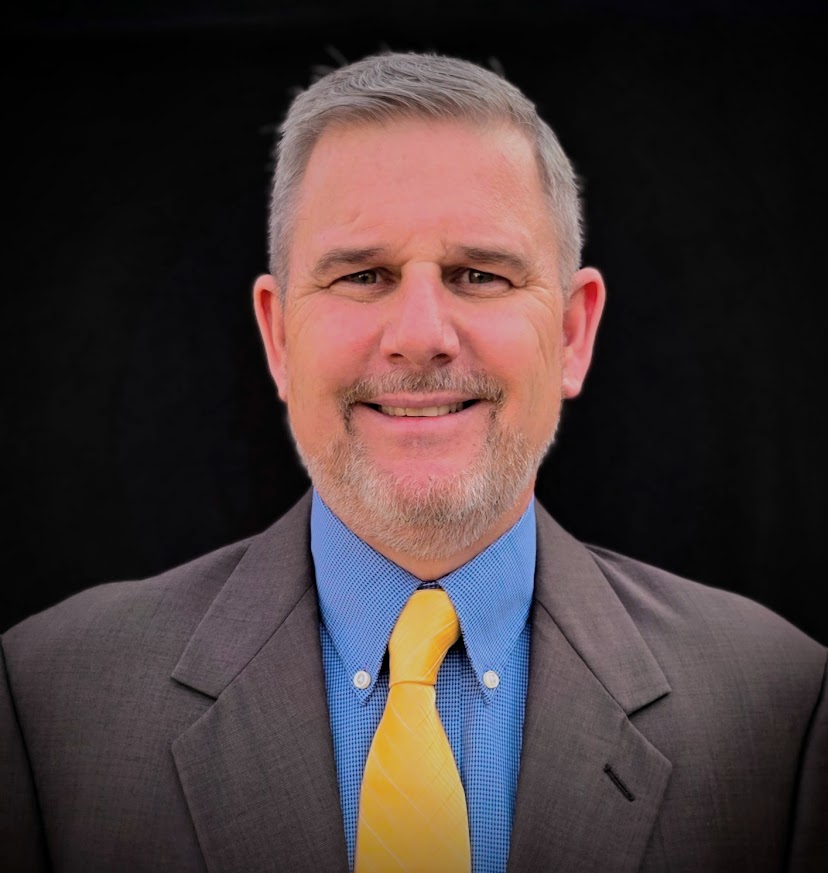
I'm James Govier, a loan officer with Lending Path Mortgage. My goal is simple: make mortgages easier to understand with honest advice, clear answers, and personalized customer service. Whether you're buying your first home, refinancing, or exploring your options, I'm here to help you make informed decisions with confidence. Homeownership should be exciting, not stressful!
13850 Ballantyne Corporate Place, Ste 380, Charlotte, NC 28277
Tel (919) 909-5941
jgovier@lendingpathmortgage.comLicensed in NC
I work with buyers and homeowners across Raleigh, Cary, Durham, and the surrounding Triangle communities. New construction and resale homes can follow different financing paths, so the loan program, the documentation you’ll need, and the timeline all depend on the property and on your situation.
The step that makes the biggest difference is getting pre-approved before you start looking. A pre-approval sets your budget, shows you what a monthly payment would actually look like, and gets your paperwork reviewed early, so you’re ready to make an offer when you find the right home.
I work closely with local Realtors and buyers throughout the Triangle. My job is to walk you through each step before it happens, so you always know what’s coming next and what’s needed from you.
You'll work with a small team, and you'll know each of them by name.
Keeps your file moving from application to processing.
The questions that come up most, answered plainly.
You can apply online or book a call with me, whichever you prefer. The application asks for basic information about your income, assets, credit, and the property you have in mind. From there, I review your information and walk you through the options that may fit your situation.
Pre-qualification is an early estimate based on the information you provide. Pre-approval goes further: I review your documentation and credit, and you receive a conditional letter you can share with sellers and agents. Neither is a commitment to lend. Final approval is subject to underwriting, an appraisal, and verification of your information.
Most applications call for recent pay stubs, W-2s or tax returns, bank statements, and a government-issued ID. If you are self-employed or have other income sources, additional documentation may be requested. I will give you a specific list based on your situation so there are no surprises.
Down payment requirements vary by loan program and by your individual qualifications. Some programs are designed for buyers with limited savings, and certain buyers may qualify for assistance programs. Once I understand your goals and finances, I can explain which options may apply to you.
A full mortgage application includes a credit inquiry. Before anything is pulled, I will explain what to expect and answer any questions. If you are early in your planning and not ready for a credit check, we can start with a conversation about your goals.
Timing depends on the loan type, how quickly documentation comes together, the appraisal, and third parties such as the title company. I will give you a realistic estimate based on your situation and keep you updated at each stage. Every loan is subject to underwriting approval, and closing dates are not guaranteed until final approval is issued.
Straight answers at every stage, from first question to closing day.
Complete our simple application in just a few minutes to get started.
We'll review your application within 24 hours and help determine the best loan options for you.
We'll guide you through every step of the process and ensure your loan closes smoothly and on time.
Let me know what you're working on and I'll get back to you on the same business day.